France's public debt has climbed past 116 percent of GDP, a higher ratio than the roughly 100 percent the United States carries in publicly held debt, and one the country is carrying without the growth America has had to help offset it. France's budget deficit sits near 5 percent of GDP, well above the European Union's target of keeping deficits under 3 percent, and growth has stayed weak even as debt has kept climbing.
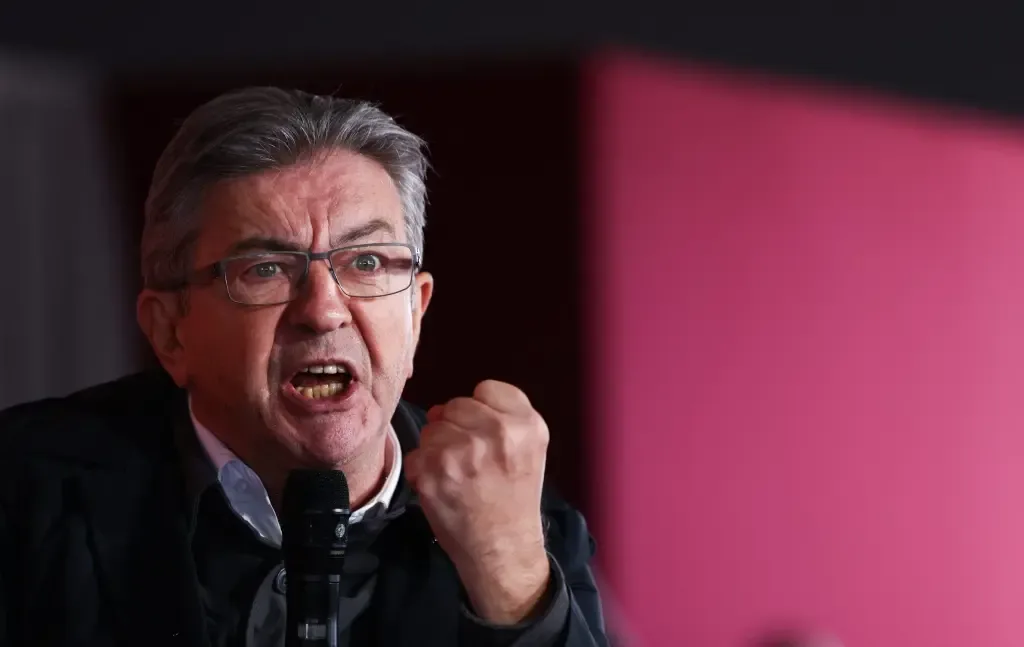
Into that backdrop has come a proposal from Jean-Luc Melenchon, the far-left candidate whose polling has him on track for a runoff against Marine Le Pen in next year's presidential election. Melenchon is campaigning on having the Banque de France simply cancel the government debt it holds. "All we have to do is take the 18 percent held by the Bank of France and chuck it in the fire," he has said, arguing the move would free up government resources for social spending.
The idea has drawn a sharp rebuke from outside France's borders. Bundesbank president Joachim Nagel warned that the plan runs directly against eurozone rules, saying "no central bank in the Eurosystem nor the ECB is allowed to cancel national debt." Nagel described the proposal as a form of monetary financing of government, a practice barred under European treaties, and warned that pursuing it could risk setting off hyperinflation.
Bond markets are already pricing in some of that risk. The spread between French and German 10-year bond yields has widened to around 88 basis points, approaching its highest level since Europe's 2012 sovereign debt crisis. Analysts watching the spread say a break above 90 basis points would be read as a signal of deeper, longer-term concern about France's fiscal path, one with the potential to spill over into how investors price risk across other European sovereign debt markets.
The stakes go beyond campaign rhetoric. France needs to raise more than $360 billion in the bond markets this year alone, financing that depends on investors continuing to trust the government's debt as a safe, predictable asset. A serious push toward unilateral debt cancellation, even one still confined to a candidate's platform rather than policy, complicates that borrowing calculus at exactly the moment France can least afford it.